S
Stacy Ann Stephens | REALTOR® · Investment Property Specialist · Mortgage Broker NMLS #1933745
Keller Williams Realty Winter Park · 147 W Lyman Ave, Winter Park FL 32789 · 407-603-1664 · License #BK3393979
Here’s the conversation I have every week with Central Florida landlords: “I want to sell. But I bought in 2018 for $210,000, it’s worth $480,000 now, and I really don’t want to write a check to the IRS for $40,000.” That instinct is exactly right. And there is a legal, IRS-sanctioned solution that has existed since 1921 — the 1031 exchange.
I’m not a tax advisor, and this guide is not a substitute for your CPA and Qualified Intermediary. But as a REALTOR® who works with investment property sellers regularly, what I can do is help you understand the real estate side of the exchange — so you go into the conversation with your tax advisor already knowing what questions to ask.
How a 1031 Exchange Actually Works — Plain English
🎙️ Direct Answer — Voice & AI Search
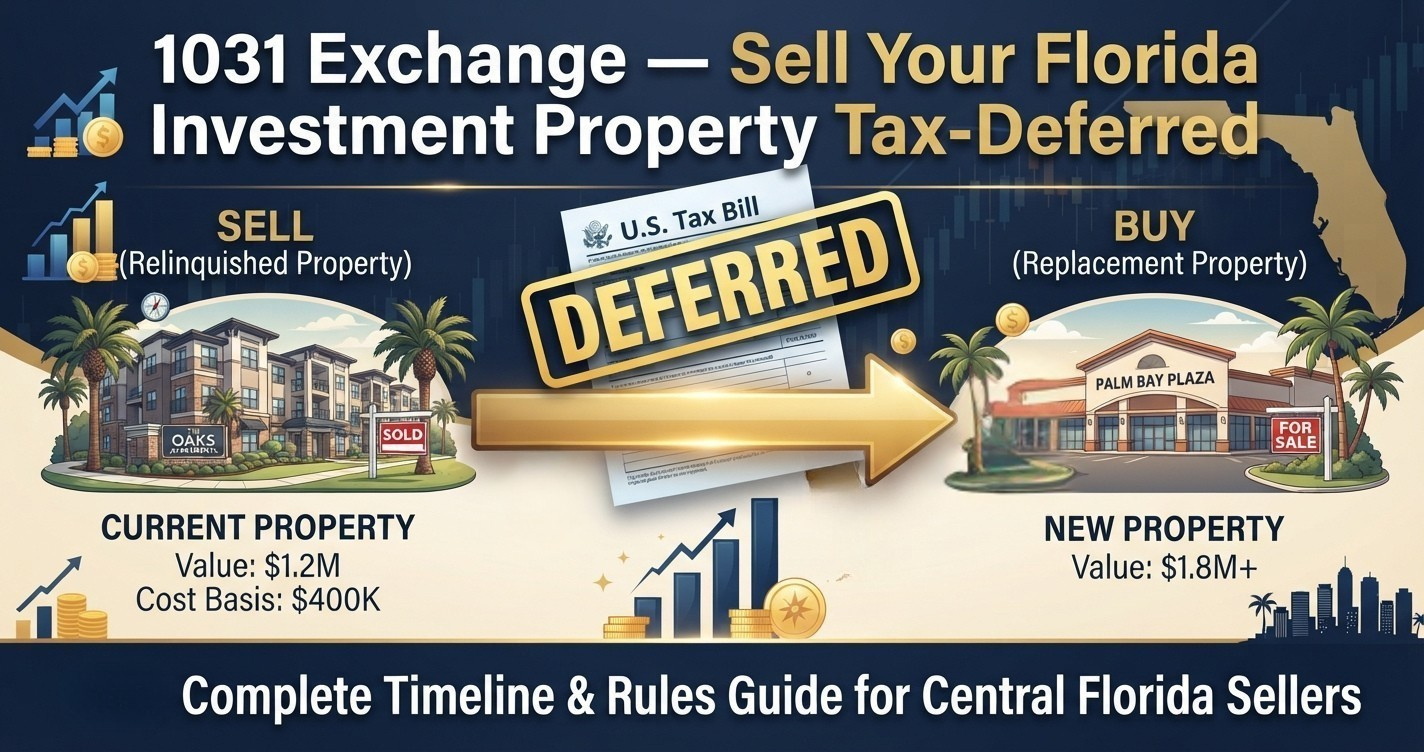
A 1031 exchange — also called a like-kind exchange — is a provision in the US tax code (IRC Section 1031) that allows an investor to sell an investment property and defer federal capital gains taxes by reinvesting the entire proceeds into a qualifying replacement property. To qualify, both the property being sold (the relinquished property) and the property being purchased (the replacement property) must be held for investment or business purposes, not personal use. The exchange must be structured through a Qualified Intermediary who holds the sale proceeds — the seller cannot receive the cash directly. The investor has 45 days from the closing of the relinquished property to identify replacement properties in writing, and 180 days to close on the replacement property.
The 3 Numbers Every 1031 Exchanger in Florida Needs to Know
- 45 days: From the day your relinquished property closes, you have exactly 45 calendar days to identify your replacement property in writing to your Qualified Intermediary. No extensions except for federally declared disasters.
- 180 days: From the day your relinquished property closes, you must close on your replacement property. The 180-day window runs simultaneously with the 45-day identification window — it doesn’t restart after identification.
- 100%: To fully defer taxes, you must reinvest all of the net proceeds and acquire replacement property of equal or greater value. Any proceeds you keep (called “boot”) are taxable.
The 5 Core Rules — What Qualifies and What Disqualifies a 1031 Exchange
🎙️ Direct Answer
The core requirements for a valid 1031 exchange in Florida are: both properties must be held for investment or productive use in business (not personal residence or vacation property); the replacement property must be of like-kind to the relinquished property (in real estate this is very broadly interpreted — any US real property qualifies as like-kind to any other); a Qualified Intermediary must hold the proceeds during the exchange — the seller cannot receive the funds; the investor must identify replacement properties within 45 calendar days; and the investor must close on the replacement within 180 calendar days. To fully defer all taxes, the replacement property must be of equal or greater value to the relinquished property and all net proceeds must be reinvested.
✅ Investment/Business Use
Both the property you sell AND the property you buy must be held for investment or business — not as your primary residence or vacation home. Single-family rentals, multifamily, commercial, raw land, and STR investment properties all qualify.
✅ Like-Kind Property
In real estate, “like-kind” is interpreted very broadly. Any US real property can exchange for almost any other US real property — single-family rental to apartment building, rental home to commercial, land to rental property, rental to NNN lease.
✅ Qualified Intermediary Required
A QI (also called an Exchange Facilitator or Accommodator) must be engaged BEFORE the relinquished property closes. The QI holds your proceeds during the exchange. You cannot use your CPA, attorney, or real estate agent as your QI.
✅ Equal or Greater Value
To defer all taxes, your replacement property must be worth at least as much as the relinquished property and you must reinvest all net proceeds. If you buy for less or keep some cash, the difference (called “boot”) is taxable.
🚫 No Primary Residences
You cannot exchange your primary home. However, a property that was your primary residence but has been rented for at least 2 years may qualify. The rules around converted properties are nuanced — consult your tax advisor.
🚫 Florida Does Not Require State Conformity
Florida has no state income tax — so unlike California or other states, there is no additional state capital gains tax concern in Florida. The 1031 exchange defers only federal taxes; in Florida, that’s the only tax to defer.
The 5 Most Common 1031 Exchange Mistakes Florida Investors Make
⚠️
Not engaging a Qualified Intermediary before closing. This is the most common and most costly error. If you close on the sale without a QI in place and the proceeds hit your bank account, the exchange is disqualified. There are no do-overs. Engage a QI as soon as you decide you want to exchange — ideally before you even list.
⚠️
Not having replacement properties in mind before selling. Sellers who list and sell without knowing what they’re buying often spend the 45-day identification window in a panic. In Central Florida’s current market, 45 days to find, evaluate, negotiate, and go under contract on a replacement property is tight. Start your replacement property search before or simultaneously with listing the relinquished property.
⚠️
Identifying more than 3 properties without understanding the 200% rule. The basic 1031 rule allows you to identify up to 3 replacement properties of any value. If you identify more than 3, you must purchase 95% of the identified properties’ combined value — almost never practical. Stick to 3 or fewer identification choices unless your tax advisor advises otherwise.
⚠️
Trading down in value and creating “boot.” If you sell for $450,000 and buy for $390,000, the $60,000 difference (boot) is taxable — even in a 1031 exchange. Many investors don’t understand this until the tax bill arrives. Either fully reinvest into equal or greater value, or understand the partial tax bill you’ll owe on any boot.
⚠️
Closing on the replacement property after the 180-day deadline. Missing the 180-day deadline disqualifies the entire exchange. The full capital gains tax becomes due for the year of the original sale. The deadline does not extend for holidays, weekends, or lender delays — build in buffer and work your closing backward from day 175 to be safe.
Do not attempt a 1031 exchange without a Qualified Intermediary and a CPA engaged before your sale closes. The exchange mechanics — holding agreements, assignment of contracts, identification letters — must follow IRS-compliant procedures. An improper exchange is no exchange at all, and the full tax bill comes due. I can refer you to QIs and CPAs who specialize in Florida investment property 1031 exchanges.
Sell. Reinvest. Defer. Repeat. The 1031 Exchange Is the Engine of Long-Term Wealth Building.
I represent the real estate side of 1031 exchanges — listing the relinquished property, identifying and showing replacement properties in Central Florida, and coordinating the closing timelines to meet IRS deadlines. And as a Mortgage Broker, I can finance the replacement property. One trusted advisor for both sides of the transaction. Let’s start the conversation before you list.
📞 407-603-1664 — Free 1031 Exchange Strategy ConsultationFrequently Asked Questions
How does a 1031 exchange work in Florida?+
A 1031 exchange in Florida works the same as in any other US state: an investor sells a qualifying investment property (the relinquished property), the net proceeds are held by a Qualified Intermediary, and the investor has 45 days to identify a replacement property in writing and 180 days to close on it. Because Florida has no state income tax, the 1031 exchange in Florida defers only the federal capital gains tax — there is no Florida state tax component to defer. This is actually an advantage relative to states like California, where a second layer of state capital gains tax exists. The replacement property must be held for investment or business use and must be of equal or greater value to fully defer all taxes.
What properties qualify for a 1031 exchange in Florida?+
For Florida real estate investors, virtually any US real property held for investment qualifies as like-kind to any other US real property held for investment. You can exchange: a single-family rental for an apartment building; a rental home for vacant land; a short-term rental for a commercial NNN property; a duplex for a multifamily building. The like-kind standard in real estate is very broadly interpreted — unlike in other asset classes where the rules are more restrictive. What does NOT qualify: your primary residence, property held primarily for sale (a flip), or a vacation home you use personally for more than 14 days per year.
What is the 45-day rule for a 1031 exchange?+
The 45-day rule requires you to formally identify your replacement property — in writing, signed, delivered to your Qualified Intermediary — within 45 calendar days of the date your relinquished property closes. There are no extensions for weekends, holidays, or lender delays. Missing this deadline disqualifies the entire exchange and the full capital gains tax becomes due for the year of the sale. Most exchangers identify up to 3 properties (the “Three Property Rule”) to give themselves backup options. The identification letter must specify the replacement property clearly enough that it can be identified from the description — typically the property address.
Do I have to use all the money from my 1031 exchange?+
To defer all capital gains taxes, yes — you must reinvest all of the net proceeds from the sale into the replacement property or properties. Any portion of the proceeds you retain (called “boot”) is taxable in the year of the exchange. Boot can be cash you receive directly, a mortgage you pay off at closing without replacing with a new mortgage, or any other consideration received. You can choose to take some boot intentionally — accepting that you’ll pay tax on that portion — while deferring the tax on the reinvested amount. This is sometimes called a partial 1031 exchange.
What happens when I eventually sell my 1031 exchange replacement property?+
When you eventually sell the replacement property without another 1031 exchange, all the deferred capital gains from previous exchanges become taxable — plus any additional appreciation on the replacement property. The 1031 exchange defers taxes; it does not eliminate them permanently. However, many investors chain multiple 1031 exchanges throughout their investment career, continuously deferring until they pass the property to heirs through their estate — at which point the stepped-up basis at death eliminates all the deferred gains entirely. For long-term real estate investors, the combination of 1031 exchanges and estate planning can result in the deferred gains never being taxed at all.
Your Investment Property’s Equity Deserves a Strategy, Not Just a Sale.
Whether you’re looking to sell a Central Florida rental and identify replacement properties in Orlando or beyond, or you need to understand the financing options for a 1031 replacement purchase, I help investment property sellers navigate both sides of the exchange. Free consultation before you list — the conversation that prevents costly mistakes.
📞 407-603-1664 · NMLS #1933745 — Free 1031 Strategy CallS
Stacy Ann Stephens | REALTOR® · Mortgage Broker NMLS #1933745
KW Winter Park · 407-603-1664 · License #BK3393979 · This post is educational information only and does not constitute tax advice. Consult a CPA and a licensed Qualified Intermediary for guidance specific to your exchange. Jhenesis Mortgage NMLS #2532705.